


CAN YOU FEEL THAT? The millionaires all around you?
They’re there—in your local car dealerships, your town’s repo business, your favorite grocery store chain. They might even be in your backyard as we speak, enjoying a neighborhood potluck.
This is the thesis of a new book, The Everywhere Millionaire, which also, incidentally, feels like it’s everywhere right now—proof of a strong, coordinated press rollout that understands its target audience (me).
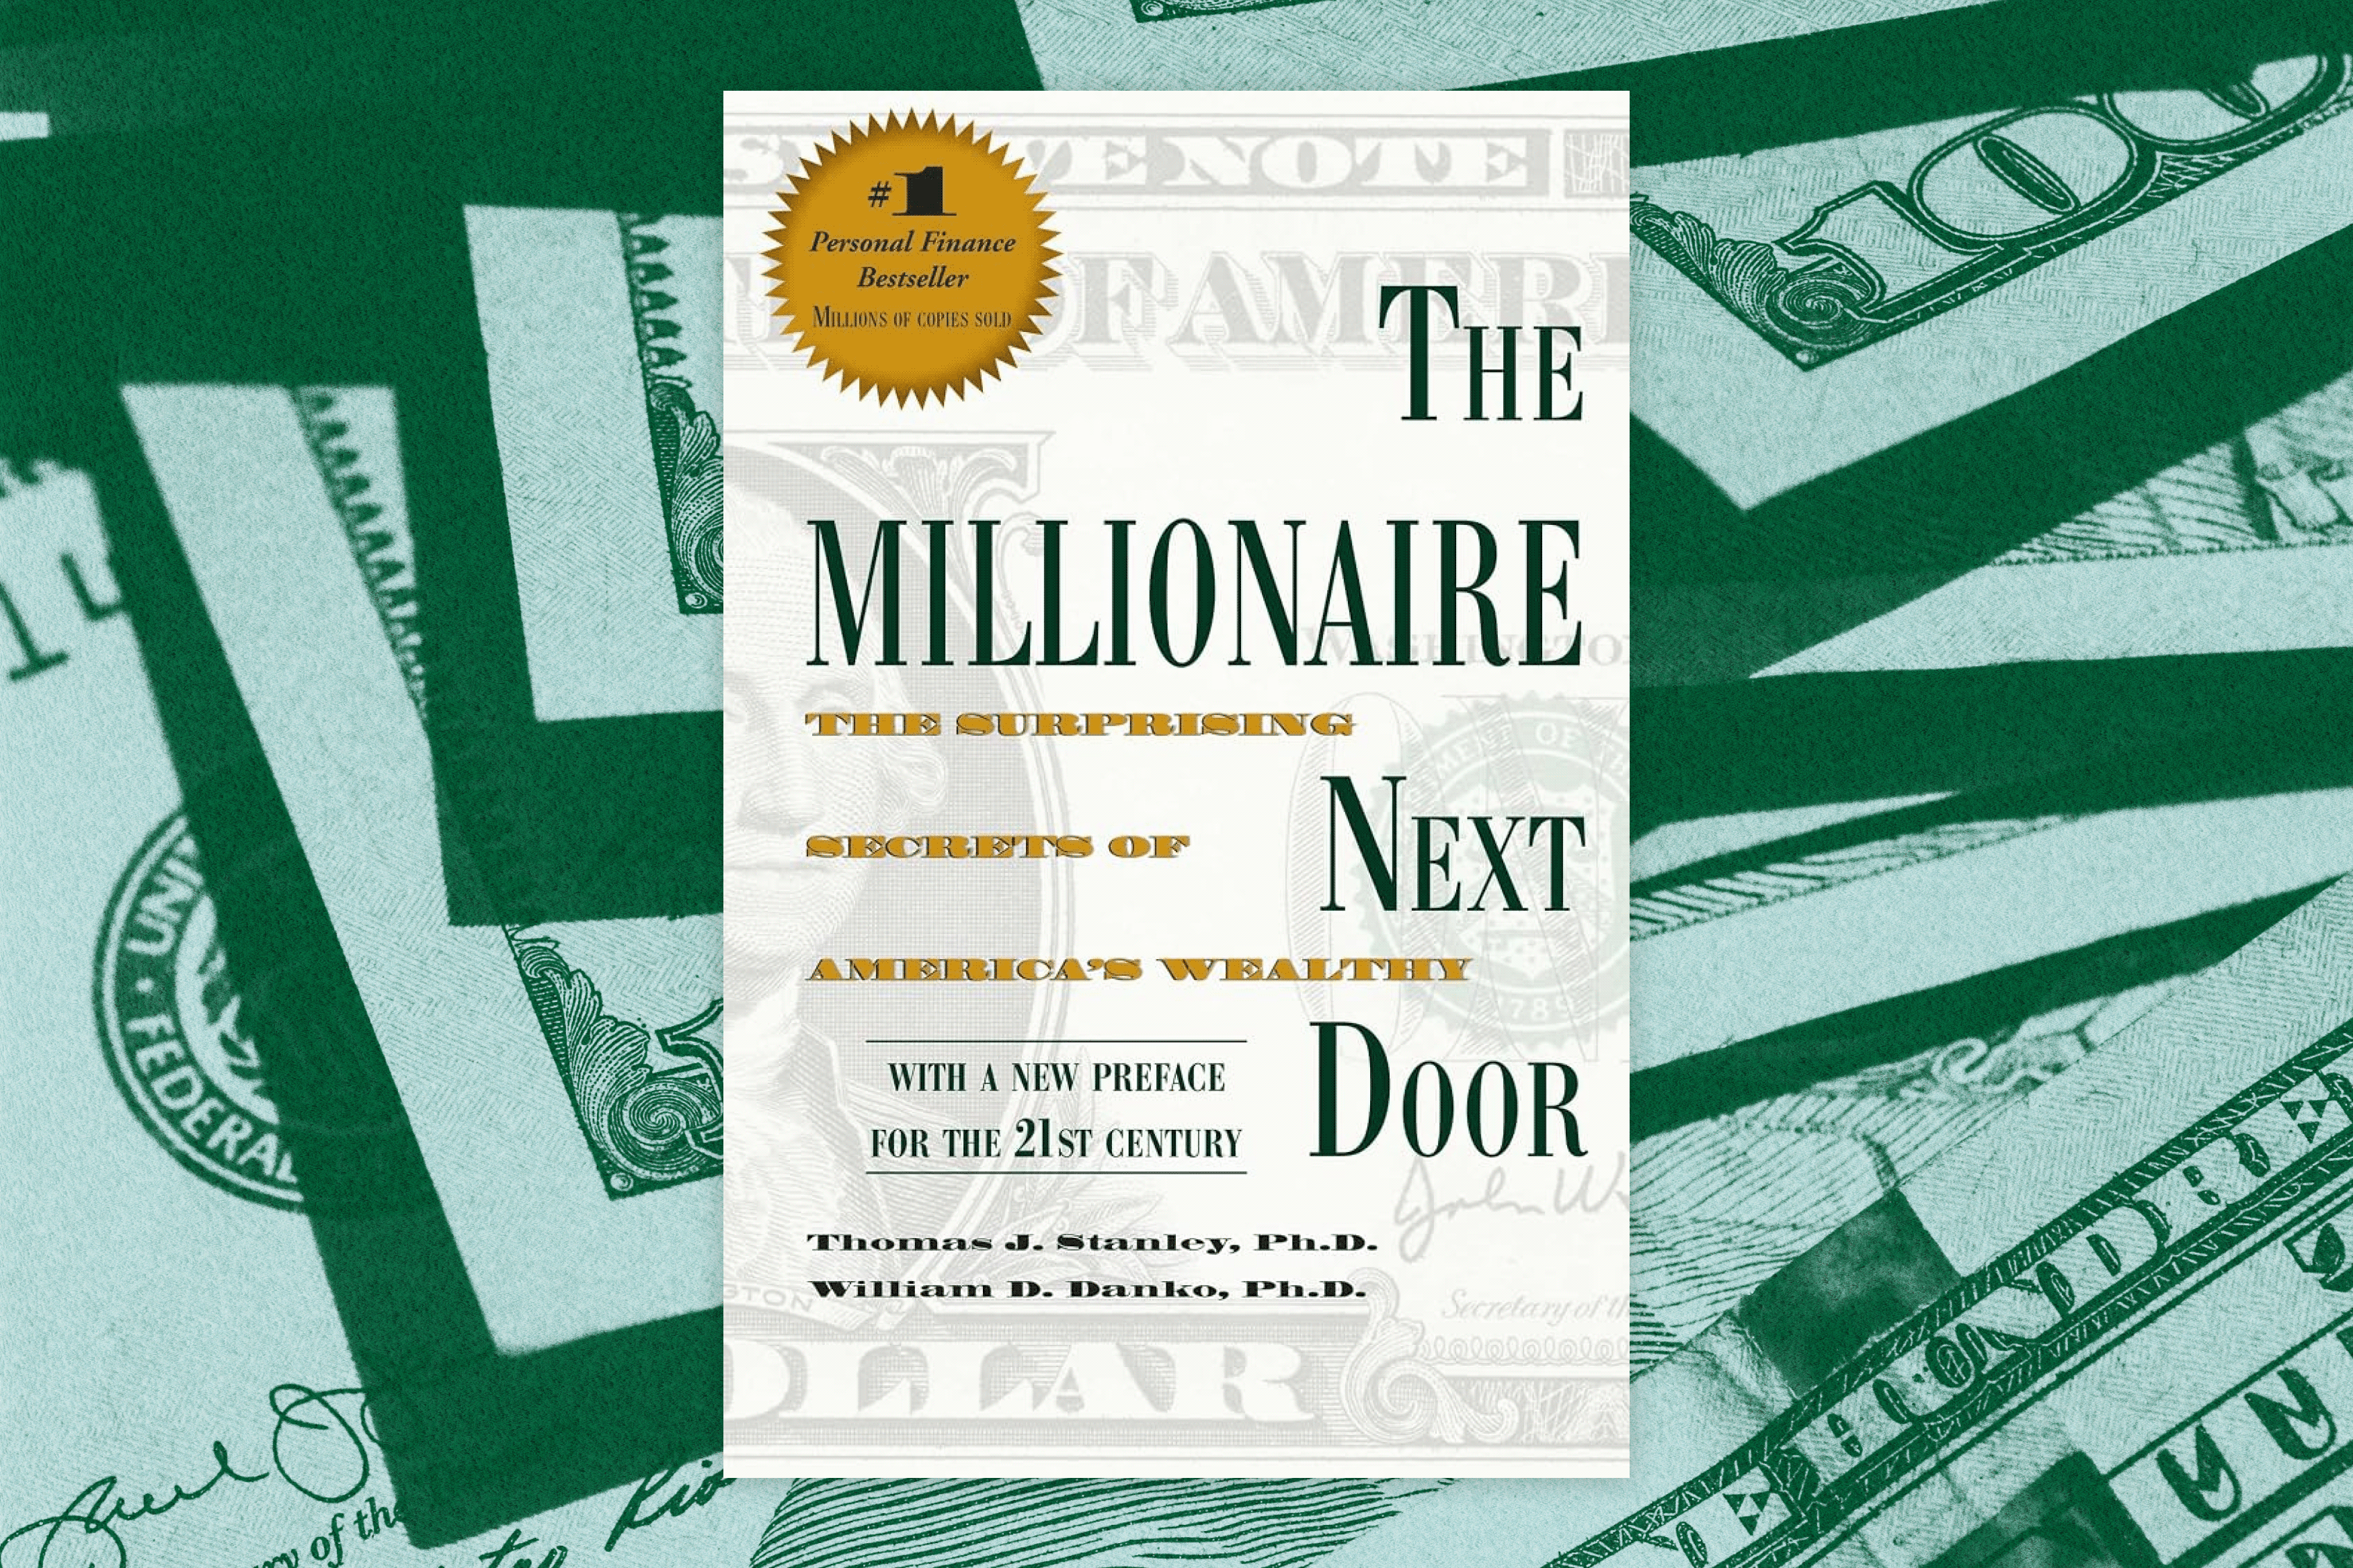
The book is the most recent addition to the “millionaire manual” genre, which exploded about 30 years ago with the bestseller The Millionaire Next Door, and then racked up titles like The Millionaire Mind (2000), The Millionaire Real Estate Agent (2004), The Automatic Millionaire (2006), The One Minute Millionaire (2009), The Instant Millionaire (2010), How to Think Like a Millionaire (2010), Quit Like a Millionaire (2019), From Zero to Millionaire (2023), Main Street Millionaire (2024), and Millionaire Mission (2024), among others.
Central to the Millionaire Cinematic Universe’s latest blockbuster is a claim that struck me, at first, as completely preposterous, the sort of statistic that knocks your worldview off-kilter: Roughly three million Americans, whom the book dubs its “Main Street Millionaires,” collectively own 13x as much wealth as the 400 richest Americans on the Forbes list.
In the popular discourse, authors Zidar and Zwick point out, we tend to focus on the centibillionaires, and the fact that the average Forbes list member is something absurd like 577x richer than the average Main Street Millionaire. But Zidar and Zwick argue that total controlled wealth—and the diffuse nature of this petite bourgeoisie—is a distributive reality we ignore at our peril. Not just because of what they tell us about the nature of inequality, but seemingly because they can also teach us how to get rich.
Zidar and Zwick developed this argument after years spent parsing the endless columns and rows of disparate tax data collection systems, connecting the tax records of private businesses with those of individual owners. Et voilà, they realized that the only people in the American economy compensated more handsomely than those in the executive suites of our multinationals are private business owners. “For every CEO of a public company,” they write in The Atlantic, “there are more than 1,000 private-business owners with a net worth of more than $25 million.”
This legion of decamillionaires is, they argue, the group that actually runs our country, influencing the regulatory environment and carving out niche exemptions in the tax code. In other words, they are the architects of inequality. One bookkeeper quoted in the book calls owning a small business “the best tax deal in America.” Here’s Zidar and Zwick in The Atlantic again:
“The [One Big Beautiful Bill Act] made permanent a 20 percent deduction that effectively lowers the top tax rate for private-business owners from 37 percent to 30 percent. And it preserved a loophole that lets business owners in most of the country, but not salaried employees, deduct their state and local taxes in full.”
In this case, “run our country” is not just a turn of phrase. The New Yorker review points out that decamillionaires hold 12% of congressional seats, despite making up less than 1% of the population. Our representative democracy isn’t very representative, though the idea that the government has ever been representative of the people it governs is ahistoric. Obvious race and gender disparities aside, the government was “erected by and for the small entrepreneurs” from the very beginning of American history, writes C. Wright Mills in White Collar (1951), a defining midcentury text about the emergence of the salaried office worker.
MOST STRIKING TO ME, though, are the parallels between the portraits of subjects in The Everywhere Millionaire and those in its spiritual daddy, The Millionaire Next Door. One such example: “They are the ‘stealthy wealthy,’” Zidar and Zwick write, “and they are hiding in plain sight.” They are also, apparently:
“...coaching your child’s soccer team, sitting next to you at community fundraisers, or chatting with you at neighborhood barbecues. They might be the dentist who expanded his office to a regional network of practices, the commercial HVAC contractor whose trucks you see around town, or the owner of that local restaurant chain that keeps opening new locations.”
And here’s Stanley and Danko in The Millionaire Next Door:
“Usually the wealthy individual is a businessman who has lived in the same town for all of his adult life. This person owns a small factory, a chain of stores, or a service company. He has married once and remains married. He lives next door to people with a fraction of his wealth.”
You get the picture. These are family men (emphasis on “men”). They own and operate boring businesses. They aren’t flashy1; hell, they’re sitting in your backyard right now!
But even within this group, a closer look at the data suggests there’s something a little squishy about leading with folksy vignettes about the scrappy HVAC tech. According to the book’s dataset of the top 25 fields that account for $668 billion in private owner income each year, just two industries—law and finance—account for $213 billion of it, nearly one-third of the total. Dentists’ offices, on the other hand, account for just $10 billion, “specialty trade contractors” for $20 billion. But the image of your friendly neighborhood financier is a little less warm and fuzzy, and understandably nobody wants to invite general counsel2 to the barbecue.
The subjects of The Millionaire Next Door were the Baby Boomers, those born between 1946 and 1964, an enormous cohort whose coming-of-age happened to coincide with a few trends in the American economy that largely no longer hold true, like an affordable college education and a strong, still-rising college wage premium. Today, Boomers are between 62 and 80 years old. As luck would have it, that means Boomers are the unwitting subjects of this book, too. “Statistically,” the New Yorker review notes, the average decamillionaire business owner of the sort profiled in The Everywhere Millionaire is “a white, college-educated, 62-year-old man.”
But the crucial difference between the theses of The Millionaire Next Door and The Everywhere Millionaire is that the former primarily credits consumption habits (anyone can be rich if they consume prudently), while the latter focuses on earning potential (anyone can be rich if they own and operate a successful private small business). In that respect, The Everywhere Millionaire is a more faithful representation of the cause-and-effect that determines who “gets rich” in America, and as a theory of inequality, it’s compelling and useful.
It seems strange, then, that Zidar and Zwick go to such great lengths to identify the eye-popping generosity of the “best tax deal in America,” only to elide all that structural nonsense in the book’s recommendations section. As Nico Taylor points out for The Baffler, this decision is surprising, until you notice that the book is, slyly, marketed not just as an “economic detective story,” but as a “roadmap to riches,” a tax analysis that veers, seemingly involuntarily, into that all-American genre of self-help.
RATHER THAN SUGGESTING we close the litany of tax loopholes that allow owners to accumulate wealth much more rapidly than workers and which lead to the inequality that Zidar and Zwick detail with such precision and care, their curiously mild proposals seem to amount to: We should provide the means for everyone to become a small business owner who may take advantage of these lucrative loopholes. Here’s Taylor for The Baffler again, summarizing some of the suggestions:
“That means ‘mentoring programs’ for ‘aspiring entrepreneurs’ and an education system that provides ‘fluency in math, accounting, and financial literacy’ as well as ‘communication’ and ‘social skills’ to help with networking. Budding entrepreneurs, with the right opportunities, are helpfully advised to ‘save,’ ‘profit,’ and ‘reinvest.’ Government and industry might chip in—the authors suggest government-provided health care, a higher minimum wage, and profit sharing—but only to benefit firms and facilitate entrepreneurship.”
It’s at this point that the book’s argument3 appears indistinguishable in its goals from the existing “main street millionaire” lane of the business book superhighway.
Codie Sanchez’s emblematic Main Street Millionaire, for example, promises to teach readers how to buy and operate businesses in “the unsexy but reliably profitable industries—like plumbing, construction, cleaning, electrical—that white collar workers4 have overlooked,” a near 1:1 match for the “roadmap to riches” component of The Everywhere Millionaire.
But it’s Sanchez’s new book, the more menacingly titled Own or Be Owned, that inadvertently names the trouble with applying this advice as though it’s a universal salve. Own or Be Owned purports to teach how to “build a business so good it doesn’t need you.” Of course, implied in this arrangement are the workers. Your unsexy main street business “doesn’t need you” because, and only because, you have employees, unless ChatGPT is towing clunkers and performing routine sewer line maintenance now.
Concluding a book that’s largely about tax-code-mediated inequality between owners and workers with recommendations for cultivating “aspiring entrepreneurs,” then, sidesteps this fundamental binary of capitalism: Owners need workers. Part of the reason two million American business owners have $10 million or more apiece is because many tens of millions more people work for them. Even in the most pollyanna, small-town-USA configuration wherein every single one of these decamillionaires pays their employees high wages (a reality I would happily prefer to the existing one), this inescapable truth remains. As Codie Sanchez and, come to think of it, Karl Marx put it, you can either own or be owned.
In these books and others like them, the recommendations are, statistically and logically, not unlike arguing that better high school football coaches will produce more careers in the NFL. Sure, some high school athletes will go pro—and more coaching might affect who gets one of the 1,696 active roster spots—but many more of the 1.1 million high school players will not.
Is it necessarily bad to aspire to something statistically unlikely? Of course not. But as a society’s leading theory of broad prosperity for either 16-year-old athletes or roughly 150 million workers, it leaves something to be desired: scalability.
Any book, then, that attempts this magic trick runs headfirst into a mathematical impossibility. The three-million-strong ranks of Everywhere Decamillionaires are proof of this limitation, not a rebuttal to it. That’s a lot of people, and still, less than 1% of the population. Majority of the 99% will have to look elsewhere for answers.

Domain Money’s CFP® professionals helped one client save more than $70,000 in lifetime taxes by switching an annual $7,000 contribution from a brokerage account to a Roth IRA.
This is the best time to start year-end planning. Domain Money made a 2026 End-of-Year Checklist to help, complete with:
Relevant deadlines (some accounts cut you off on December 31, others extend through the tax filing deadline)
2026 contribution (and catch-up) limits for every account
Key year-end dates to remember, like when to start donating appreciated stock or tax-free gifts
Backdoor Roth IRA conversions, getting the most from your 401(k), topping up any HSA payroll contributions, and tax-loss harvesting all benefit from starting early. Head into the holidays this year with the confidence that your personal finances are in the best shape possible.
I Love You But I’ve Chosen Darkness is autofiction from Claire Vaye Watkins that feels spiritually reminiscent of Miranda July’s All Fours. It’s so surreal and beautiful and gross (complimentary). The metaphors are breathtaking. At one point she describes a character trailing off at the end of the sentence with an ellipsis (…) “like a stone skipping across a pond,” and I actually gasped. This novel rescued me from a bout of creative malaise at the perfect time. (Was legitimately listening to self-help podcasts; that’s when you know shit is bleak.) I don’t understand why the Goodreads reviews are so low. (Riverhead Books)
Really strange piece about how 9/11 inaugurated what the writer calls the “Orange Era.” I enjoyed the way he played with the disorientation of misremembering and the sensory experience of the 21st century. (n+1)
Just started watching The Beast in Me about a writer (Claire Danes) who gets a new nepo-real-estate-developer neighbor (Matthew Rhys) who—maybe—killed his wife. Psychological thrillers hit different in the fall. (Netflix)
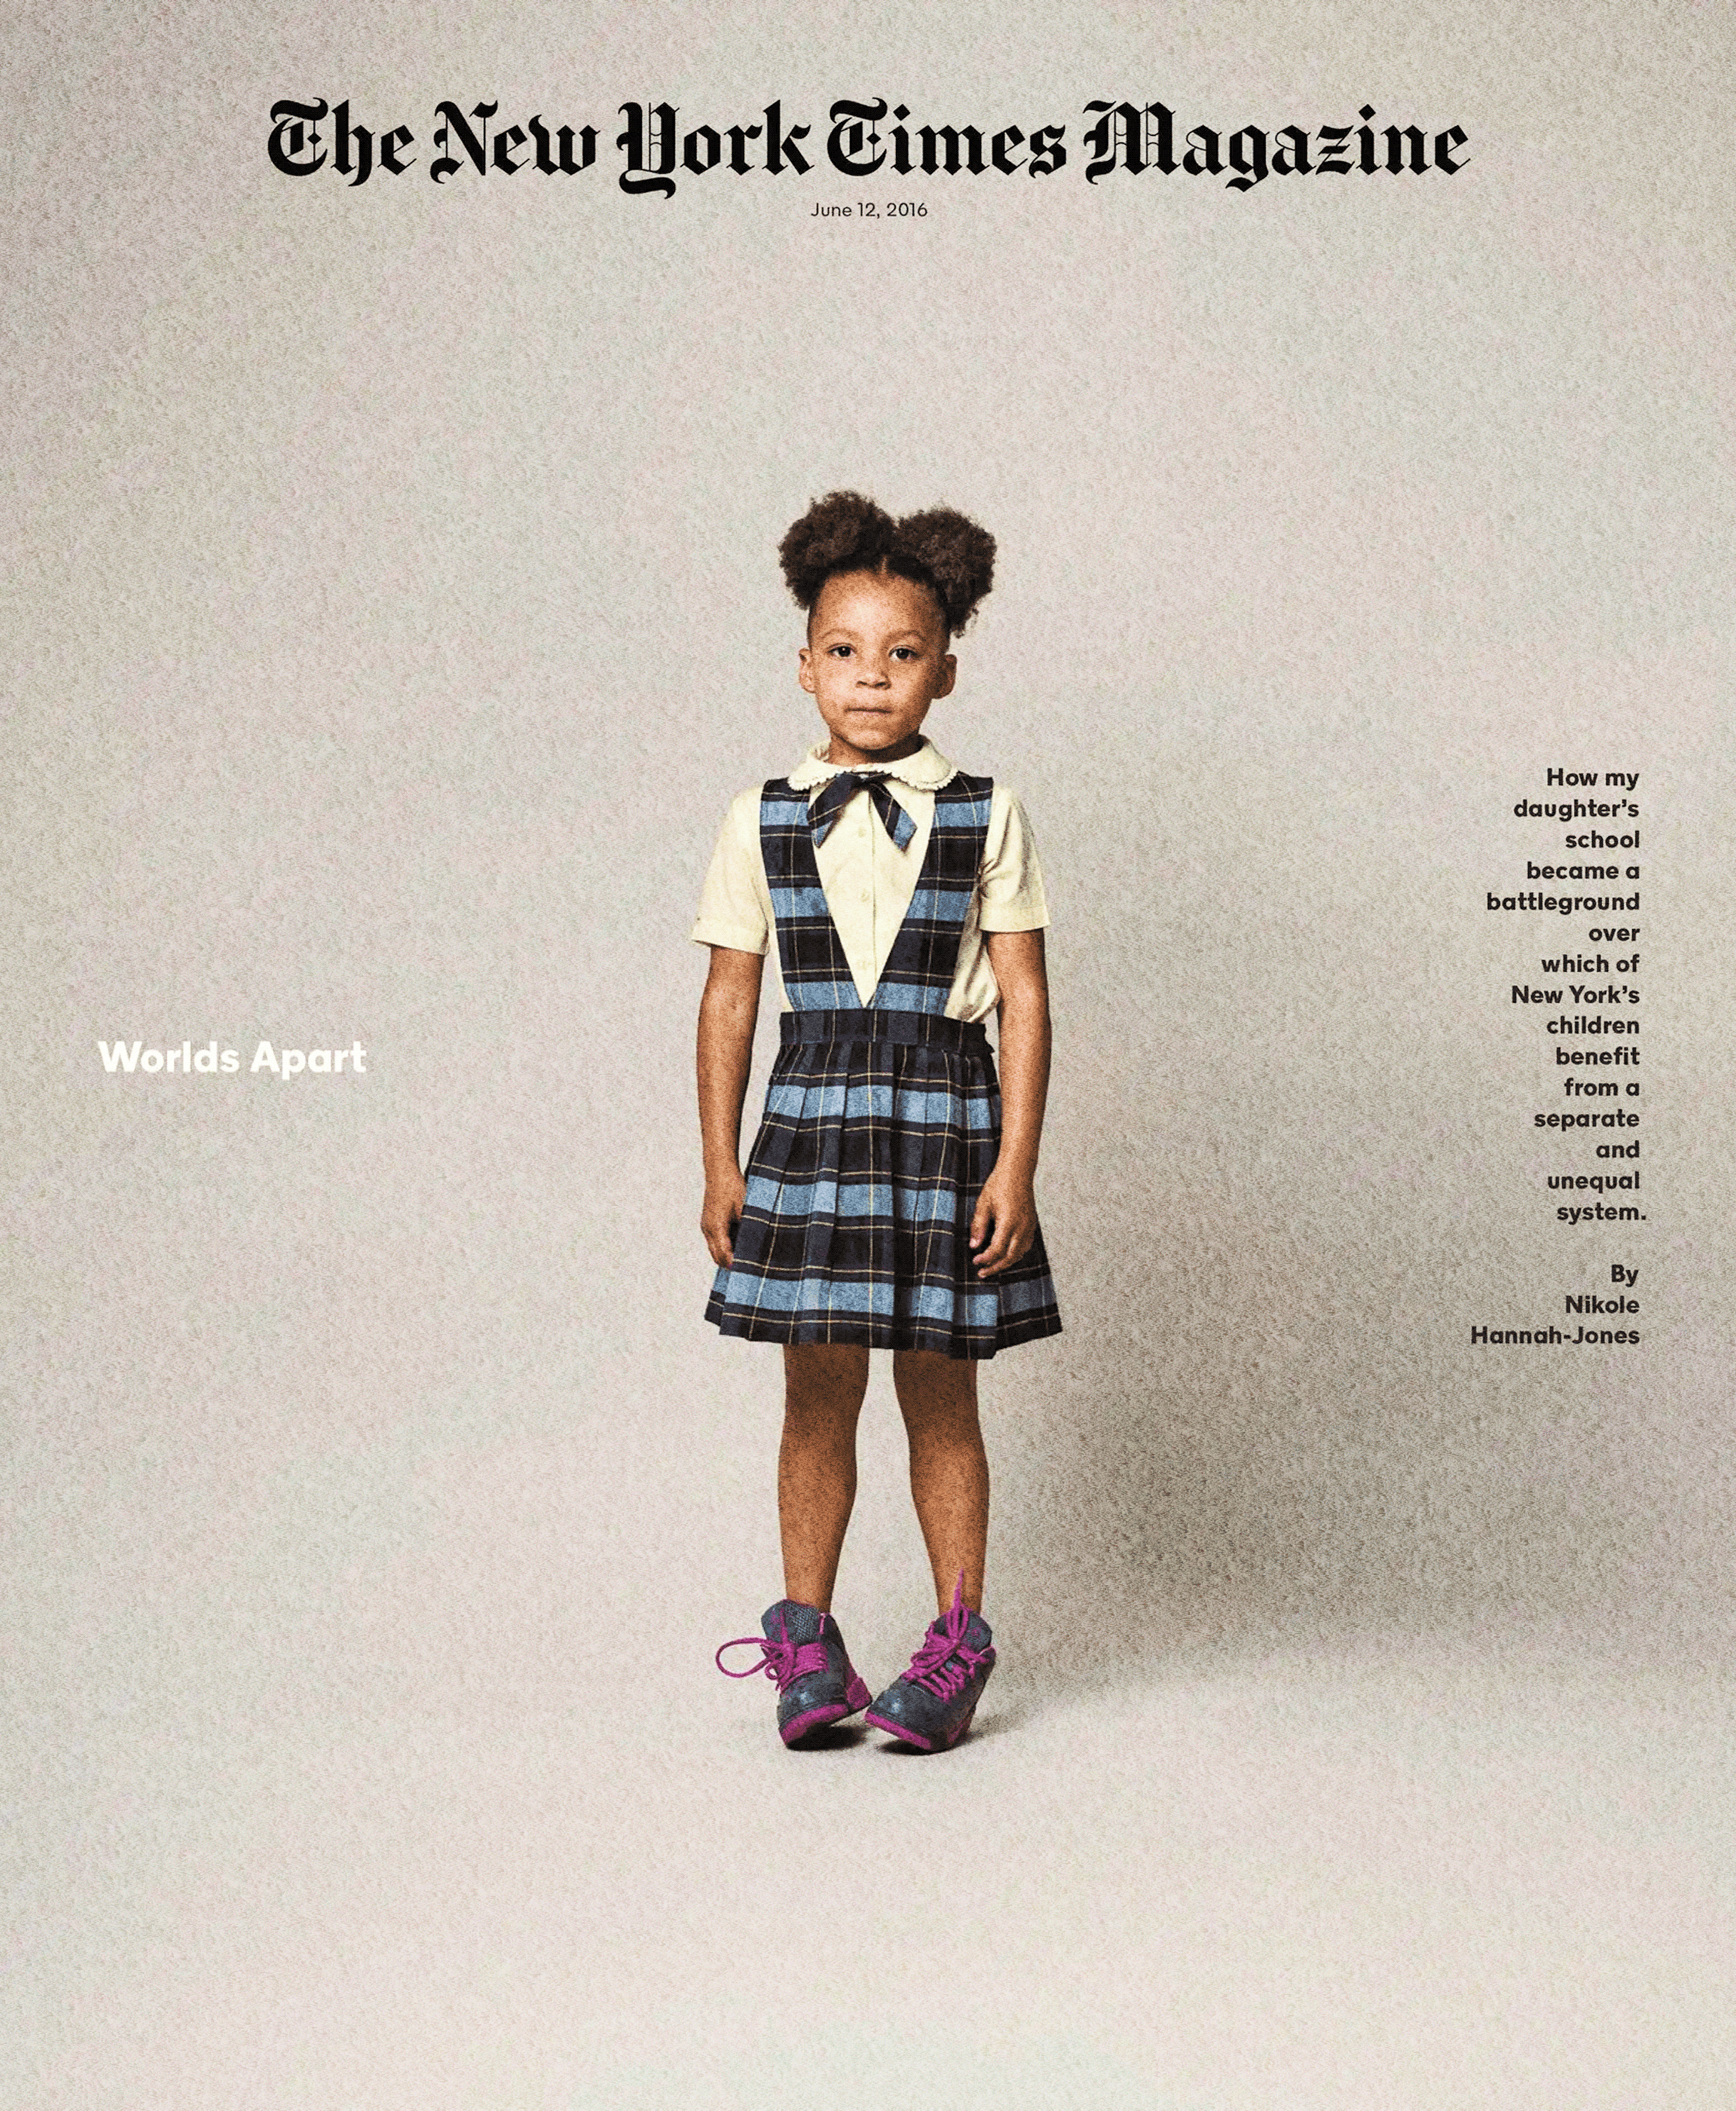
On Sunday, a New York Times staff writer published a powerful, 10-year follow-up essay about her decision to enroll her daughter in a so-called “bad” school. In 2016, Nikole Hannah-Jones wrote a long piece of reporting for The New York Times Magazine about the ugly realities of school segregation in New York City, the most diverse public school system in the country. It changed the way many understood the issue of integration. (This is Hannah-Jones’s beat. I remember when, during my sophomore year at the University of Alabama, she published an exposé about the methodical segregation of a Tuscaloosa high school.)
An upper-middle-class Black employee of the Times, Hannah-Jones intimately understood the injustice of concentrating privilege and opportunity in a few schools. She wrote about why she ultimately decided to send her own child to a high-poverty school in her area, thinking that she could both inoculate her daughter against the worst effects and be a positive force in the school. The alternative—using her wealth and access to whisk her daughter to a wealthier, whiter place—seemed unjust, at odds with her values. In her words:
“I understood that so much of school segregation is structural—a result of decades of housing discrimination, of political calculations and the machinations of policy makers, of simple inertia. But I also believed that it is the choices of individual parents that uphold the system, and I was determined not to do what I’d seen so many others do when their values about integration collided with the reality of where to send their own children to school.”
Her 2026 update is harrowing, vulnerable, and highlights the tragedy of a system that “puts at odds trying to be a good person with trying to be a good parent.” This saga raises such painful, irreconcilable questions: How are we to make progress when acting in the collective good is so actively disincentivized; when it feels downright irresponsible not to seek out individual advantage? Is making your children pay the price for your values an injustice of its own? I will always be interested in the way individual people and families answer these big-picture questions in the singular of their own lives. Regardless, she says, one undeniable truth remains:
“As long as we continue to rescue our own children from the failing schools where we allow other people’s children to languish simply because those children have been born Black and poor in a nation of racism and riches, there is no absolution here. Not for me. Not for you. Not for any of us.”
☑️ Snag Domain Money’s free 2026 End-of-Year Checklist. It has relevant contribution limits and deadlines, rule changes around catch-up contributions, key end-of-year dates, and more. If you’re looking for an extra pair of eyes for your end-of-year planning, schedule a free strategy session and see if a Domain Money CFP® professional is the right fit.
Advertiser Disclosure: Money with Katie is a promoter of Domain, a real client, and receives compensation in connection with sponsorship of the podcast and newsletter. This compensation creates a conflict of interest, as it may influence the content presented, including the featuring of Domain Money or its advisors. The views expressed by the promoter are their own and do not necessarily reflect the views of Domain Money. This communication is for informational purposes only and should not be construed as a recommendation, offer, or solicitation for the purchase or sale of any security.
This example assumes annual Roth IRA contributions of $7,000, a 7% average annual rate of return, and a 15% long-term capital gains tax rate applied to investment gains only. Contributions are made with after-tax dollars. Results assume no withdrawals during the 30-year period and do not account for inflation, changes in tax law, or variations in investment performance. These scenarios reflect the experience of current clients of Domain Money Advisors, LLC; individual results will vary, and past performance does not guarantee future outcomes.
The “not flashy” thing is sort of undermined when Zidar and Zwick describe how one of their Everywhere-Millionaire-Locator methods is strolling around harbors and asking yacht owners about their line of work.
I can say this because my husband is a lawyer, right?
I found a couple of papers where Zidar and/or Zwick make the case for some mild tax reforms, but it would appear these calls don’t make it into the book (or the surrounding press rollout coverage in NPR, The Atlantic, or The New Yorker). Per Taylor’s review: “If these reforms are part of their platform, they’re left unstated.”
Overlooked as these unsexy fields may be by white-collar workers, they certainly haven’t been overlooked by white-collar finance. “Private equity has moved in hard,” one deal tracker site writes, counting “roughly 800 HVAC, plumbing and electrical companies acquired by PE since 2022,” noting that the sort of “recurring, non-discretionary demand” that might prompt you to call a plumber or electrician “became a favored roll-up thesis.”
The football analogy is interesting to extend: the NFL roster spots open up every year, such that the roster turns over, keeping churn happening and keeping opportunity open. The deca-millionaire spots don't/won't work that way. These are mostly 62-year-old men sitting on closely held businesses, and the tax code is built to move those businesses down the family line rather than back into open competition. So the the odds aren't just long. Most of the soprts are already spoken for and are being passed down. 🤷🏻♀️
What we all want to see and understand, the matrix is building up a new carrot 🥕 "millionaire" as the status quo. Yes, 💯 40 years ago "middle-class" was (was) the status to have or work to have?
I have been thinking for two weeks about this new push to build up the "millionaire" status as potential (don't like that word, but) the new American Dream.
You can see how easily some of the content on YouTube is channeling this idea
Love this piece 🧩